
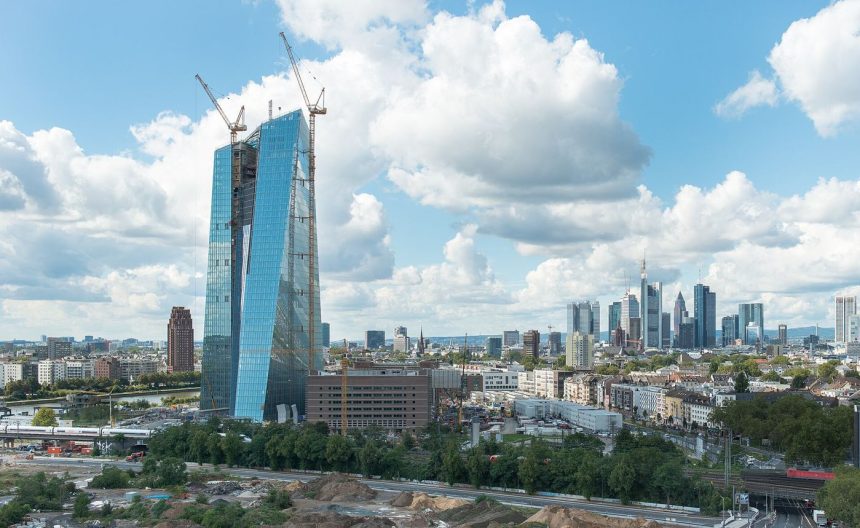
The European Central Bank has held its key interest rate steady while its president prepares to leave the job early, closing a chapter for the eurozone’s central bank. On 29 October 2026 the Governing Council kept the deposit rate at 2.5 percent, after raising it by a quarter point in September, and President Christine Lagarde said the council had debated whether a further rise was appropriate before deciding unanimously to wait for more information. Euro-area inflation had climbed to 4 percent in October, its highest in more than three years, driven mainly by energy costs. At the same time, the ECB announced that Lagarde will step down on 7 February 2027, months before the formal end of her mandate, so the December meeting will fall in her final weeks in office. Markets now price a strong chance of a rise to 2.75 percent at that meeting.
What the Evidence Shows
The decision leaves eurozone borrowers and savers in a holding pattern, with the next move depending on data that arrives before 17 December. Bundesbank President Joachim Nagel said in mid-November that another rise was highly probable if conditions did not change, and other policymakers have signalled the same direction. For households with variable-rate mortgages, a December rise would mean higher monthly payments, while savers could see modestly better returns. Lagarde has stressed that the surge in prices is mainly energy-led, and that the bank will follow a data-dependent, meeting-by-meeting approach rather than pre-committing to a path. Whoever succeeds her will inherit the same dilemma: inflation above target, growth under pressure, and a council that must choose between the two. The transition also comes at a sensitive moment for the euro, with currency markets watching every hint about the timing and size of the next move. Reporting and analysis from sources such as International Monetary Fund track the same developments, and specialists following ECB rate hold say the direction is now consistent across independent lines of evidence.
The Wider Context
The wider context is a financial system repricing risk after a long era of cheap money. Decisions shaped by ECB rate hold are being made under closer supervisory attention, with stress tests and disclosure rules that assume conditions can worsen quickly. Institutions that planned for the benign case are adjusting in public, which is uncomfortable and healthy in equal measure.
What Happens Next
What happens next with ECB rate hold will be visible first in the data that professionals watch weekly: flows, spreads and the terms on new deals. Participants who spoke for this article expect a period of adjustment rather than drama, with the biggest effects landing on those who assumed the old conditions were permanent. Planning, as ever, is the cheapest hedge. You can follow related developments in our coverage of finance.
There is a practical lesson in all of this for readers deciding what to do today. Start with the verified facts, be wary of anyone promising certainty, and prefer reversible steps while the evidence is still developing. Circumstances differ by country, income and personal situation, so general guidance should always be weighed against your own context before you act on it in any significant or lasting way.